Furniture is one of the biggest markups in retail. Here is how to time purchases, buy secondhand wisely, and avoid the financing traps that make a sofa cost twice as much.

A new couch can cost as much as a used car payment for a year, and it gets less valuable the moment it comes through your front door. Furniture is one of the most heavily marked-up categories in retail, which means it is also one of the best places to save if you know how the game works. You do not need a showroom budget to have a home that feels good. You just need a plan.
This guide covers when to buy, where to buy, what is worth paying more for, and how to avoid the financing offers that turn a $900 sofa into a $1,400 one.
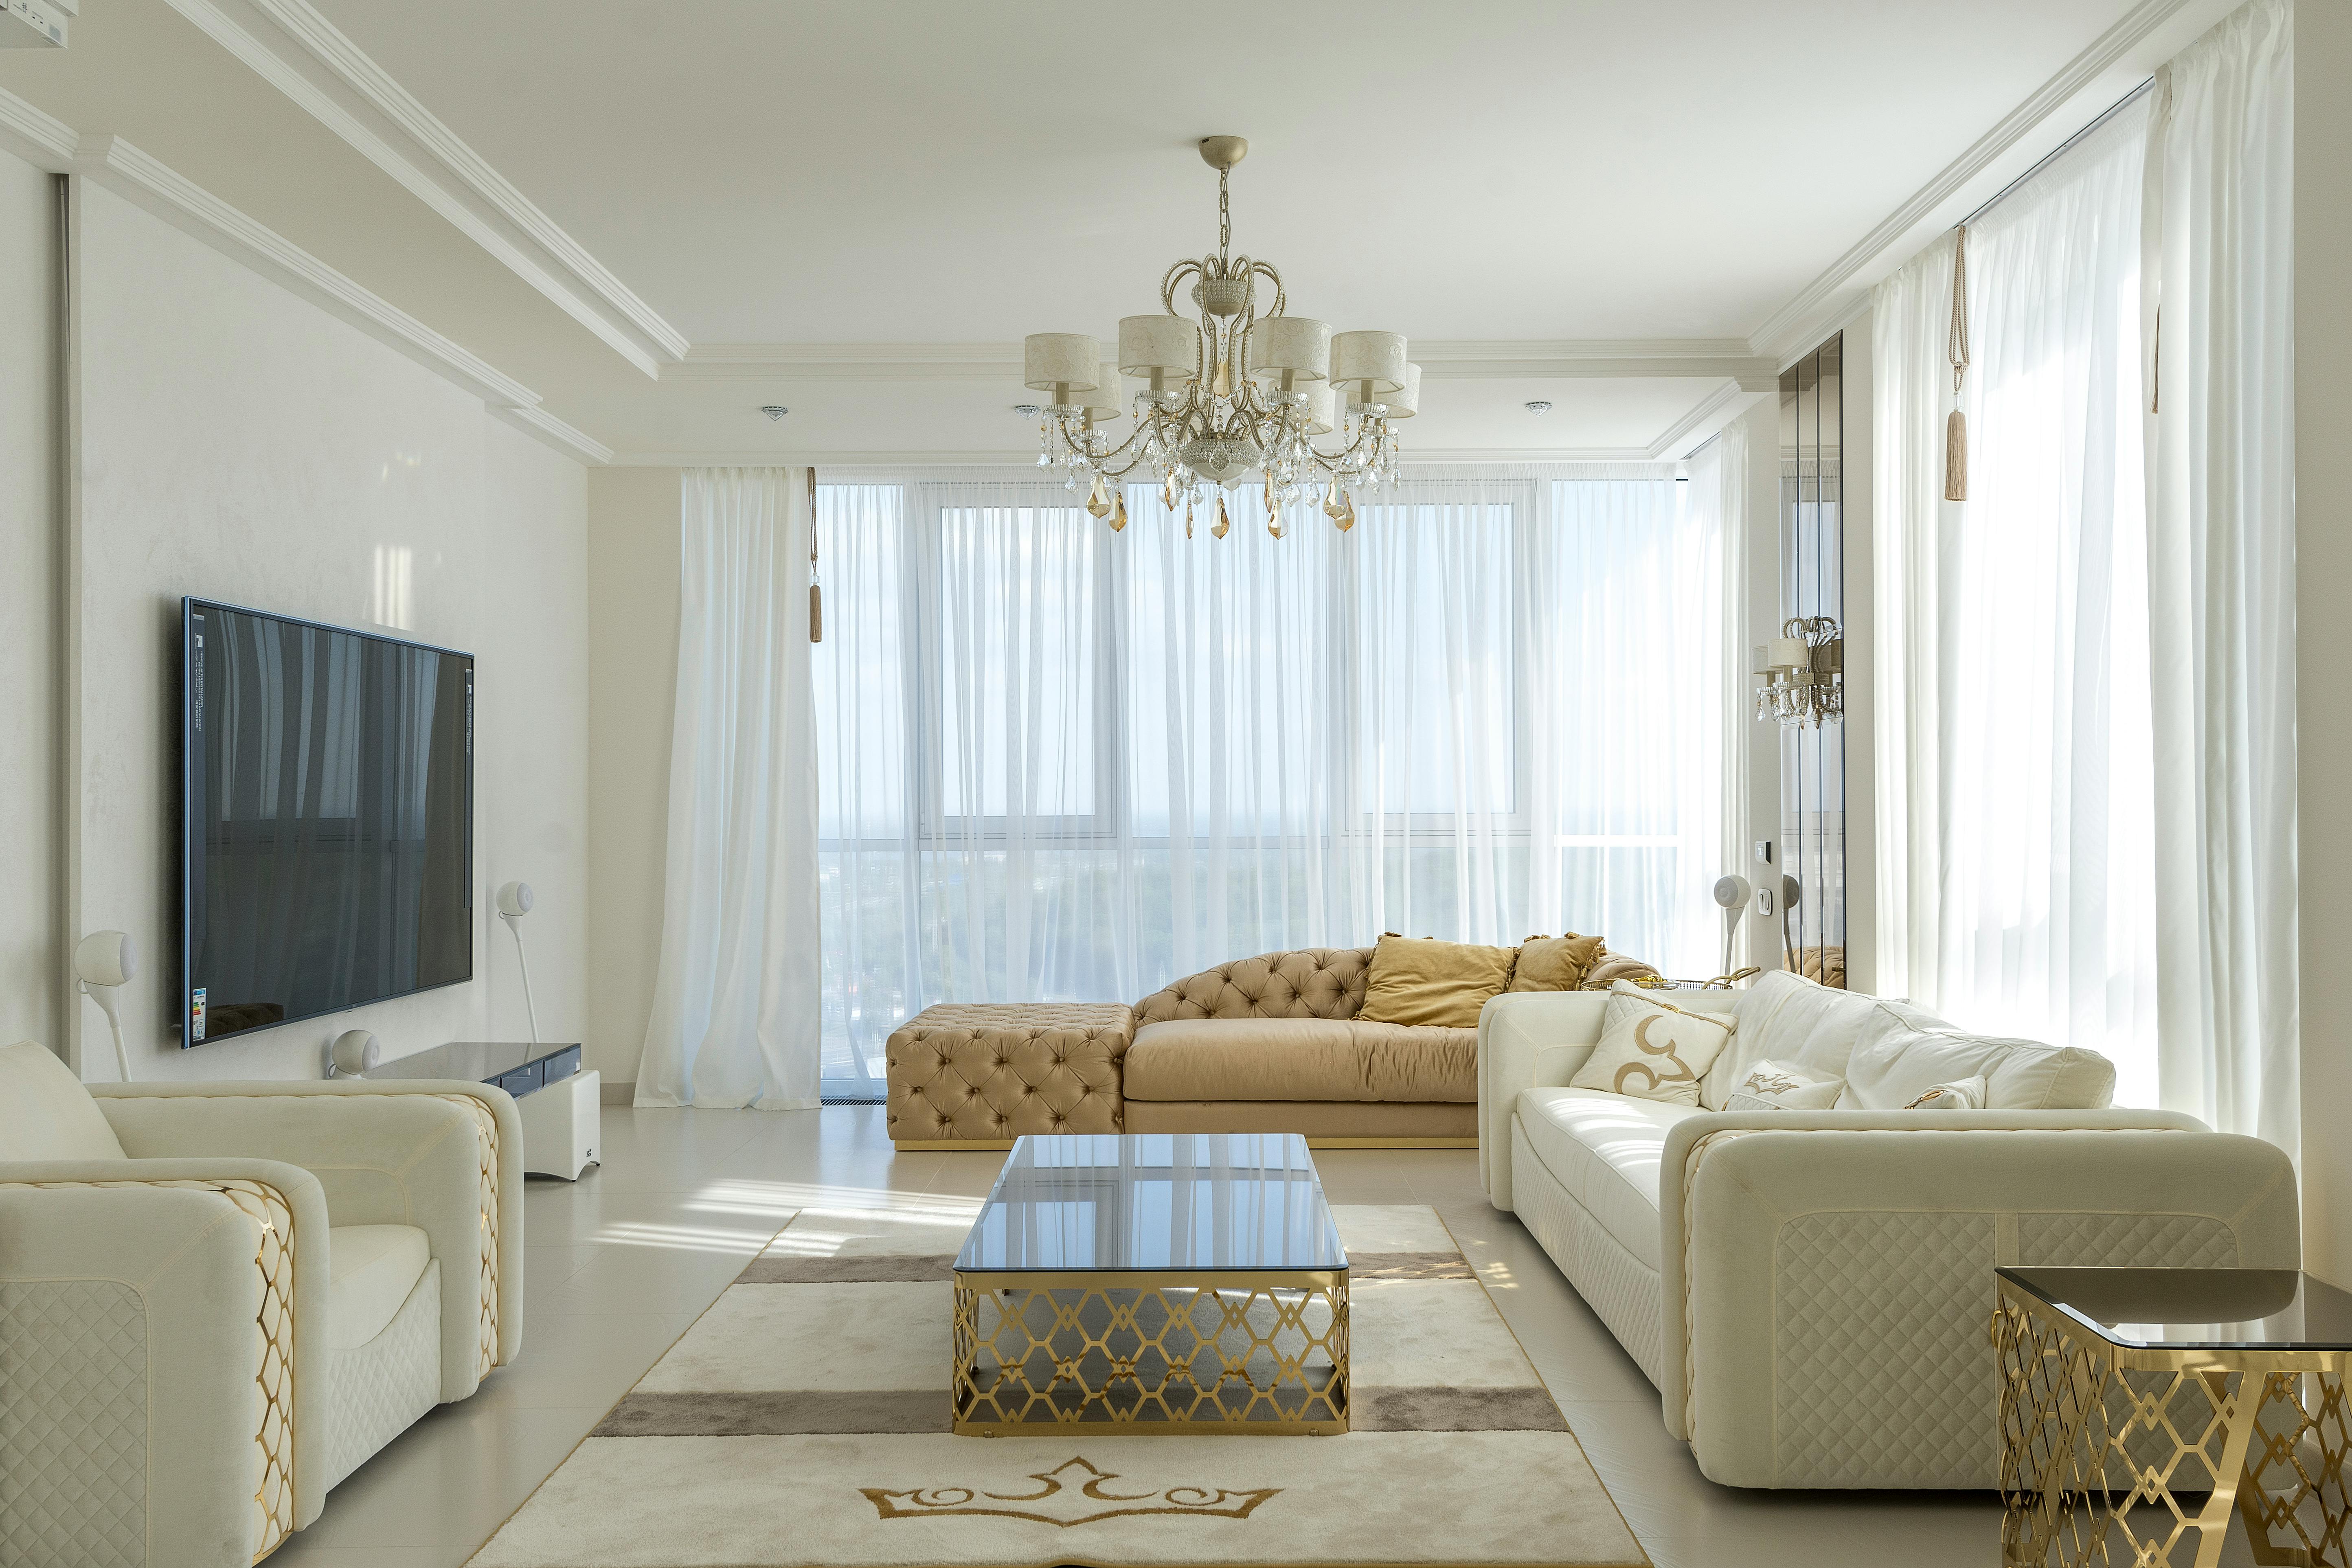
Not every piece deserves the same budget. A useful rule: spend more on things your body touches every day, and spend less on things that just sit there.
Worth paying more for: your mattress, your main sofa or sitting chair, and your desk chair if you work from home. These get used for hours daily and fail visibly when cheap.
Worth saving on: side tables, bookshelves, dressers, bed frames, and decor. Solid secondhand versions of these are everywhere, and most people cannot tell the difference.
This simple split lets you put your money where you will feel it.
Furniture sales follow a calendar. Retailers clear floor models and make room for new collections at predictable times, and the discounts are often 20% to 40% off.
Presidents' Day weekend (February): mattresses and bedroom sets.
Memorial Day and the 4th of July: broad furniture sales, especially outdoor and living room.
Labor Day (September): one of the biggest furniture sale weekends.
Black Friday and Cyber Monday: deep online discounts, though inventory can be thin.
January: clearance on holiday and seasonal pieces.
If you are not in a hurry, wait for one of these. Also ask about floor models; stores often sell them at 30% to 50% off, and small scuffs rarely show.

Secondhand is where the biggest savings live, particularly for solid wood pieces that are built better than much of today's flat-pack furniture. Good sources include local marketplace listings, estate sales, consignment shops, and "buy nothing" groups.
A short checklist helps:
Check joints and drawers. Wobbly or sticky means expensive repairs.
Sniff test. Smoke and pet odors are hard to remove from upholstery.
Look for solid wood versus particleboard. Particleboard swells when it gets wet and does not repair well.
Inspect sofas for bed bugs: check seams, under cushions, and the frame.
Measure twice. Tape the footprint on your floor and measure doorways and stairwells.
Prices are often negotiable, and a polite offer 15% to 25% below the asking price is normal. If you are interested in turning your own castoffs into cash, our look at Facebook Marketplace vs. eBay vs. Poshmark shows where resellers do best.
Many furniture stores advertise "no interest for 24 months" or "0% financing." Sometimes that is a good deal. Often it is a deferred interest plan: if you do not pay off the entire balance by the end of the promotional period, you are charged interest retroactively on the full original amount, usually at 25% or more.
A safer option, if you want to spread out payments, is a general-purpose 0% APR credit card, which charges interest only on whatever remains after the promotion ends, not on the original purchase. Compare it with a cash back card too. If you pay in full each month, you might earn 2% on the purchase, which is $20 back on a $1,000 sofa. For store credit cards in particular, the sign-up discount of 15% to 20% can look tempting, but make sure you read the terms and plan to pay the balance quickly.
Let's look at two friends furnishing their first apartments.
Jasmine has a $3,000 budget for a living room and bedroom. She wants it all done in a weekend, so she walks into a store and buys a sofa ($1,100), a coffee table ($300), a bed frame ($650), a dresser ($550), and a rug ($250), for $2,850 before tax. To make it "affordable," she signs up for the store's 24-month deferred interest plan at about $119 a month. After a rough winter she misses the final payoff by $400 of balance. The store charges her retroactive interest of about 27% on the original total. That adds about $700 to her cost, bringing her real total to roughly $3,550.
Oliver has the same $3,000 target but takes six weeks. He buys a solid wood dresser ($120) and a bed frame ($90) from local listings, a used coffee table ($45), and a floor-model sofa during a Labor Day sale ($650, marked down from $1,100). He buys a new rug on sale for $140. He pays with a cash back card that earns 2% and pays it off monthly. His total is $1,045, minus about $21 in cash back, so roughly $1,024. He ends up with a similarly furnished home for about $2,500 less than Jasmine paid, and he still has most of his budget to put toward a good mattress.
Buying everything at once. Furnish the essentials first and fill in gaps slowly; you will make better choices.
Skipping measurements. Returns and restocking fees can eat 15% to 25%.
Ignoring delivery costs. Free delivery on a $400 item may be built into the price; paid delivery can add $75 to $150.
Falling for "limited time" pressure. Furniture sales repeat several times a year.
Paying for brand names over build quality. Check the frame material and warranty rather than the label.
Start by making a list of what you need, sorted by priority. Set a total budget and split it into "spend" and "save" items. Check local listings daily for a week to learn the going prices. Mark the next big sale weekend on your calendar. For anything financed, confirm in writing whether the plan is deferred interest and set autopay for the full amount a month before the deadline. If you are building a spending plan to support all this, the 30-day rule for impulse spending is a handy brake for big purchases.
Furnishing a home does not have to drain your savings. Spend on comfort, save on everything else, wait for sale weekends, buy secondhand where it makes sense, and treat store financing with caution. A few weeks of patience can easily save you thousands.
This article is for general educational purposes only and is not financial advice. Prices, sale dates, and financing terms vary by retailer and location. Examples use fictional people and simplified numbers.
Join the newsletter your bank hates and your wallet loves.
No spam. Unsubscribe anytime.